
Notices
Legal Information
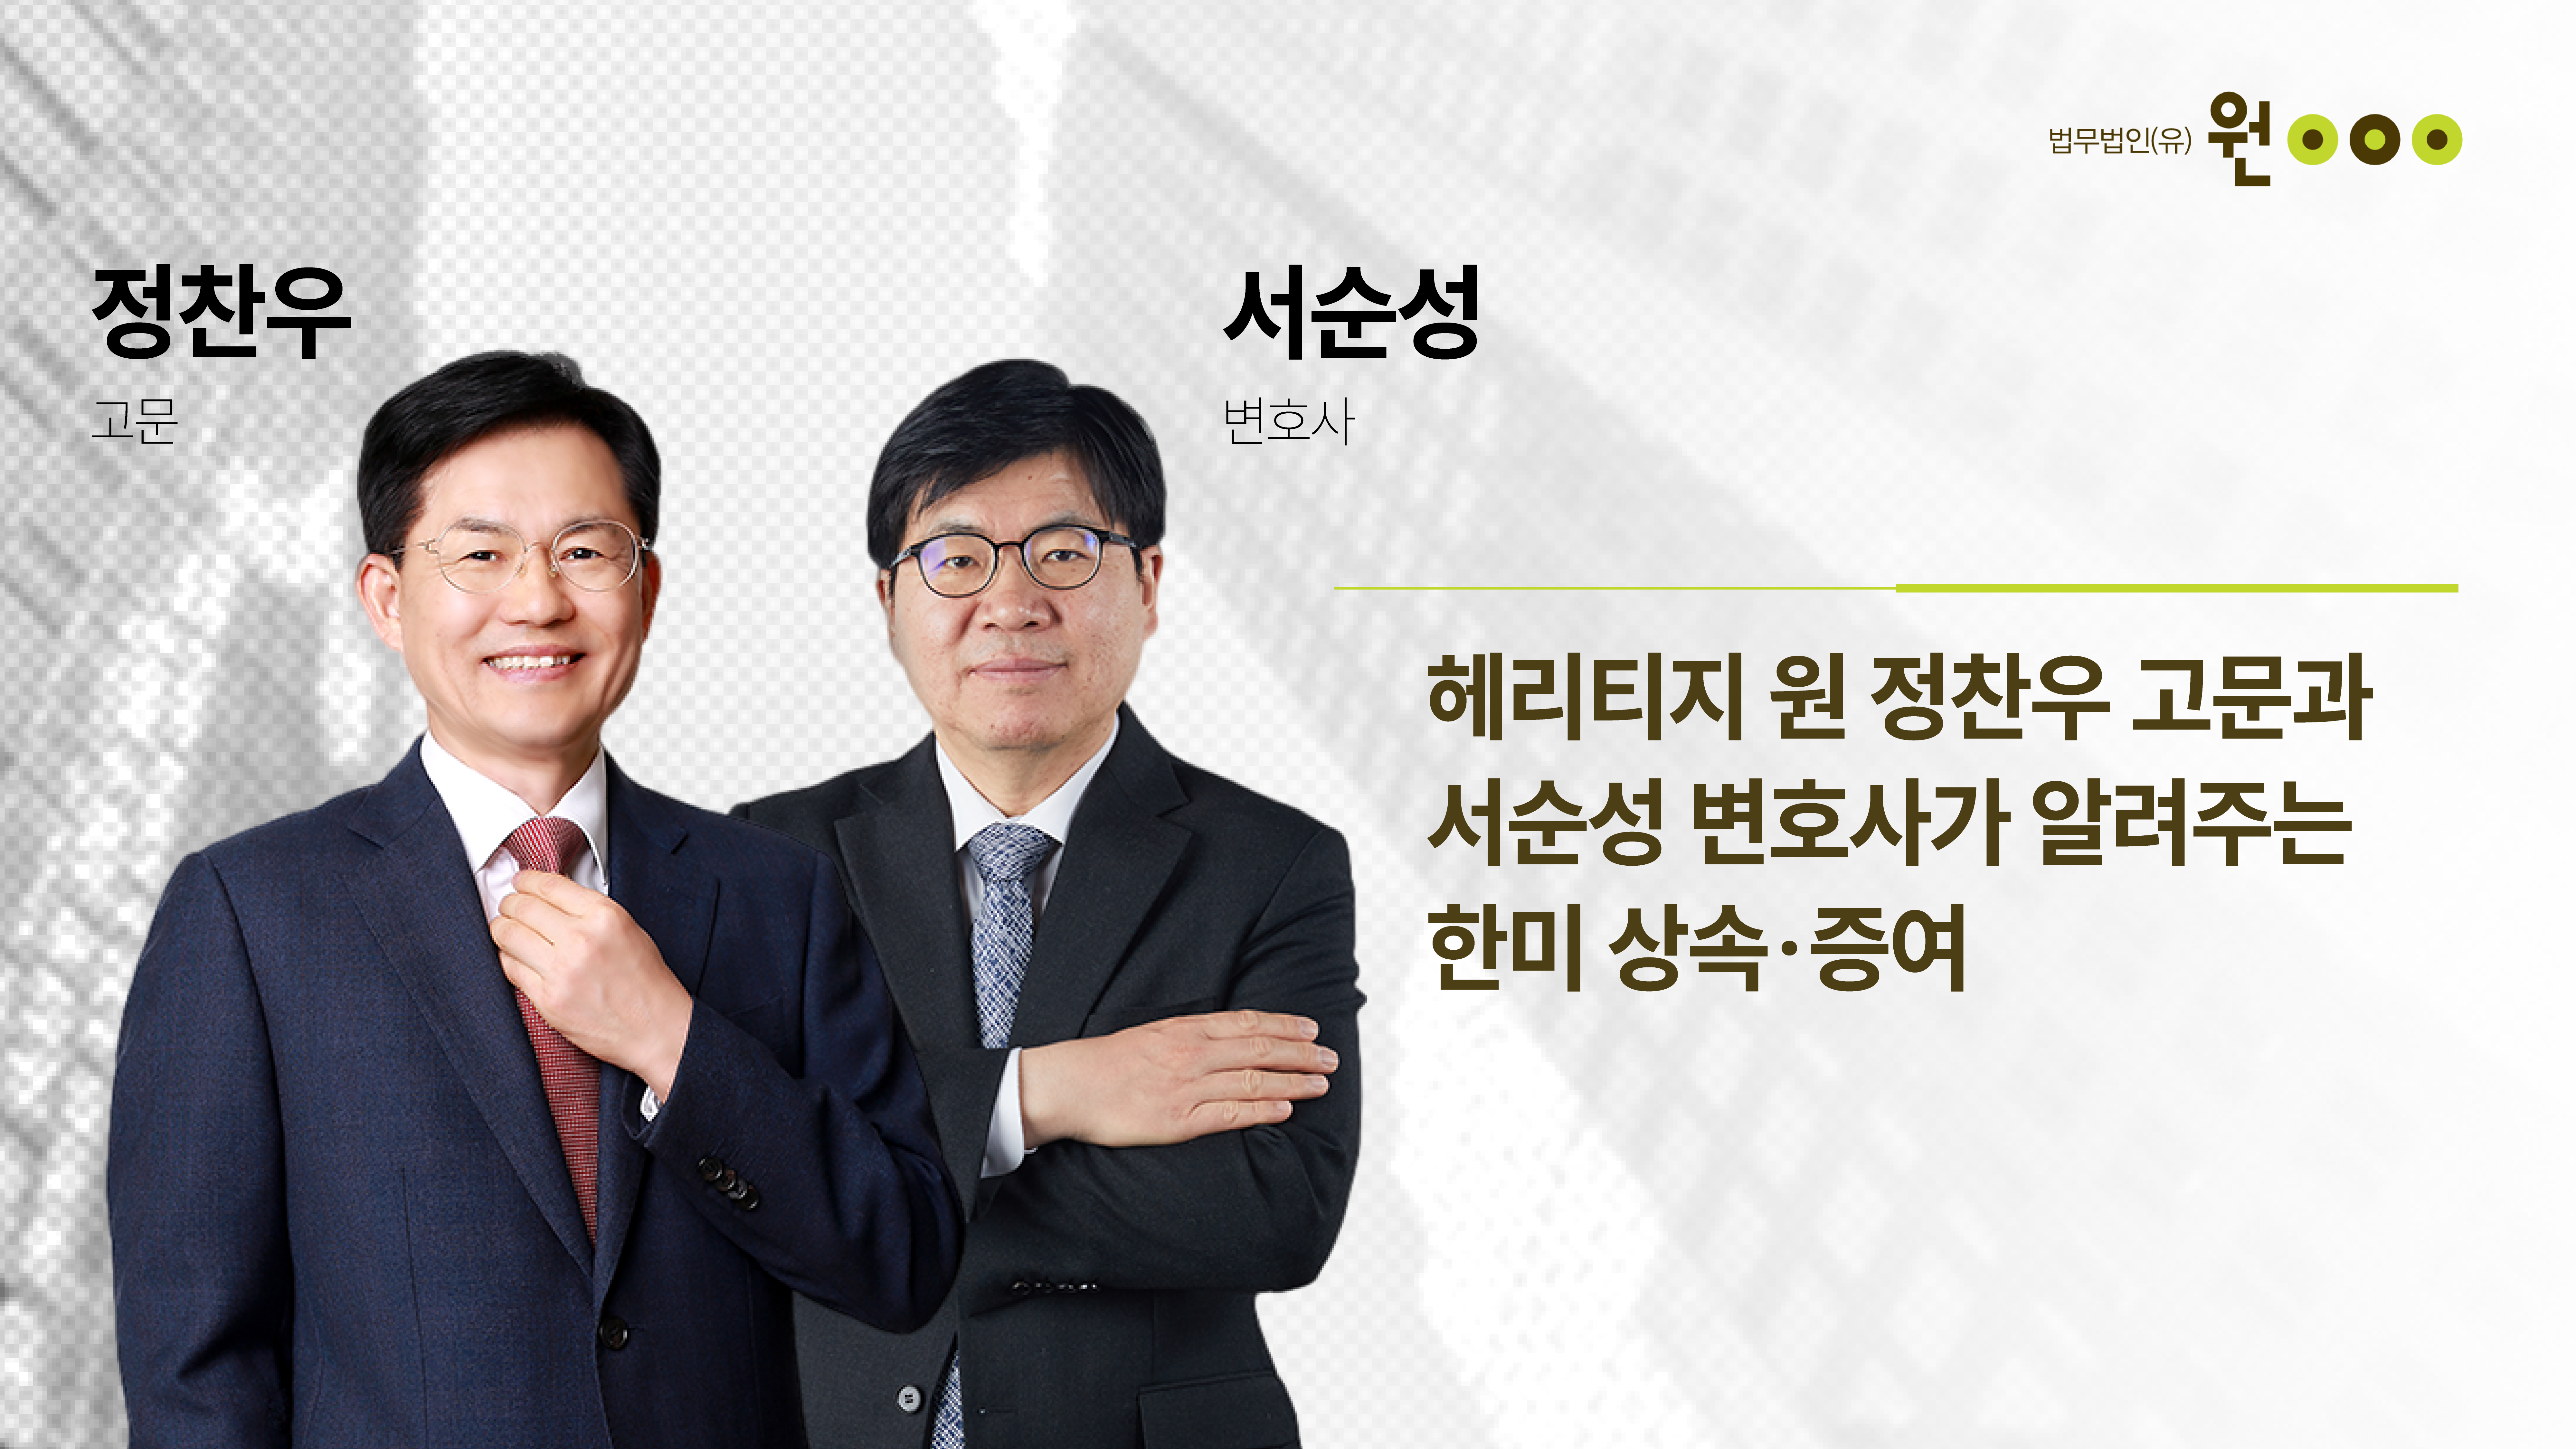
Inheritance and Gift Planning Between Korea and the United States with Attorney Soon-sung Seo and Advisor Chan-woo Jung of the Heritage One Team
Residents of the United States who maintain family members, real estate, or other assets in Korea must consider both Korean and U.S. legal and tax rules in the course of inheritance and gift planning.
Advisor Chan-woo Jung and Attorney Soon-sung Seo of Heritage One, the inheritance and family business succession team of One Law Partners, LLC, introduce the key legal and tax issues involved in cross-border wealth succession between Korea and the United States.

Recent discussions regarding tax reform in Korea have raised the possibility that certain tax benefits previously available in connection with the ownership and disposition of real estate may be reduced.
In particular, because tax liabilities may vary depending on whether changes are made to deduction programs relating to long-held real estate, advance planning and review are important.
Even where a U.S. citizen or permanent resident sells Korean real estate and pays the applicable taxes in Korea, U.S. reporting obligations may still arise.
Accordingly, individuals should consider not only Korean tax filing requirements but also their obligations under U.S. tax laws.
Before beginning inheritance procedures, it is important to accurately determine the extent of the estate, including financial assets, real estate, and liabilities.
In addition, where gifts were made prior to death, related information may often be confirmed through inheritance tax filing records.
Under Korean law, unless heirs take separate legal action, they may inherit not only assets but also liabilities.
Accordingly, it is important to verify whether the deceased had outstanding debts and consider whether a renunciation of inheritance or qualified acceptance may be appropriate.
U.S.-based individuals inheriting assets in Korea may be required to submit documents such as a signature certificate, certificate of residence, certificate of identity, and an apostille.
Because errors in documentation may delay registration and inheritance procedures, careful review is essential.
Under Korean tax law, the scope of available inheritance tax deductions may differ between residents and non-residents.
However, if an individual is classified as a Korean tax resident, overseas assets may also be taken into account, making a comprehensive review of each person's circumstances important.